Thrift Savings Plan

Screenshots
Details
- Rating
- 1.91K reviews
- Version
- 7.2.0
- Developer
- FRTIB
Analysis by Norviv
Managing a Thrift Savings Plan can become one of those chores that gets postponed for no good reason. You may only want to check your balance, review an account detail, or make a quick decision about your retirement savings, yet the task can feel too important to handle casually and too inconvenient to leave until later. I reviewed Thrift Savings Plan as a focused business app from FRTIB, and its main value is simple: it puts routine TSP access in a place that is easier to reach when you are away from a computer.
This is not an app I would describe as exciting, and that is a compliment in this category. It is built around a practical job rather than entertainment or broad financial planning. The free app has an Everyone content rating, supports devices running iOS or Android version 12 or later, and is currently at version 7.2.0. Its audience is clear: people who already have a Thrift Savings Plan and want a more convenient way to stay connected to it.
My overall impression is that the app succeeds when it replaces a browser visit with a short, purposeful check. It is less useful if you expect a complete retirement-planning suite, detailed investment education, or a substitute for professional financial advice. The difference matters because a narrow tool can be excellent at reducing everyday friction while still being the wrong choice for a larger financial decision.
Why a dedicated TSP app is useful in everyday life
I find a dedicated TSP app most useful when it turns an account check from a task I keep postponing into a quick, intentional part of my routine. The key is to decide what I need to review before opening it, especially when I’m checking in between other errands. That small habit helps preserve the convenience while making room for a more careful approach to account access and personal information.
The recurring problem is not always complicated
The difficulty with retirement accounts is often not understanding that they matter. It is remembering to check them, finding the right sign-in route, and making time for a task that does not produce an immediate result. A mobile app gives that task a more natural place in the day. Instead of waiting until I am at a desktop, I can open the account during a quiet moment and deal with the question that brought me there.
That convenience is especially helpful for small checks. If I want to confirm that my account information looks right or see where things stand before reviewing my wider budget, a dedicated TSP app is more direct than opening a general browser and searching for the correct destination. The time saved may be modest on one visit, but the reduced mental effort is the real benefit. Fewer steps make it more likely that I will check deliberately rather than keep putting it off.
There is also a useful psychological distinction between a dedicated account app and a general finance app. A broad money-management service may show balances from many institutions, but it may not be the best place to handle a TSP-specific task. Thrift Savings Plan keeps the focus on this one account, which makes it easier to separate retirement savings from checking accounts, credit cards, and day-to-day spending.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
That focus does not make it a complete financial picture. I would not use it alone to judge whether my overall retirement strategy is suitable, because a TSP balance is only one part of a person’s finances. What it does well is make the account easier to revisit. For many users, that is a more realistic improvement than adding another complicated planning dashboard.
My first useful setup
The first session should be treated as a secure account-access task, not as casual browsing. I would install the app from the official platform store, confirm that the device meets the minimum operating-system requirement, and have the account details needed for sign-in ready before starting. That preparation avoids the common frustration of beginning a financial task without the information needed to finish it.
Once access is established, I would spend a few minutes learning where the information I care about is located. The best mobile finance experience is not necessarily the one with the most screens; it is the one where the important screen becomes familiar quickly. For this app, I would identify the normal route to account information and make a habit of using that same route rather than exploring at random every time.
I also recommend deciding what “checking the account” means before opening it. A quick balance review is different from investigating a contribution issue or thinking through an investment allocation. Defining the purpose first keeps a short visit short and reduces the temptation to make a rushed decision simply because the app is convenient.
Security habits matter more here than visual polish. I would avoid signing in while connected to an untrusted network, keep the phone’s operating system current, and use the device’s normal lock and authentication protections. The app makes access more convenient, but convenience should not mean treating retirement-account access like a social feed.
What a normal day looks like with it
Imagine checking your finances on a payday. You have already reviewed your household spending, and you want to make sure your TSP account is still part of that larger picture. With a dedicated app, you can open the account, look at the relevant information, and close it without turning the task into a full desktop session. The important point is not that the app creates a new financial plan; it helps you follow through on a small piece of an existing one.
Another realistic situation is preparing for a conversation with a financial professional or reviewing your personal records. The mobile app can serve as a convenient way to look at the account before that conversation, so you are not relying entirely on memory. I would still take care to distinguish current account information from broader conclusions about retirement readiness. Seeing a figure is useful; interpreting it requires context.
It can also help when you are away from home and remember an account question at an inconvenient time. A browser may work, but the app removes the need to remember a web address or navigate through unrelated pages. That makes it a practical companion for users who prefer handling small administrative jobs immediately rather than collecting them for a weekend paperwork session.
For someone who checks retirement savings only occasionally, the app may be most valuable as a low-effort reminder of the account’s existence. I would not recommend opening it repeatedly just to watch short-term changes. Retirement savings deserve a longer view, and frequent checking can encourage emotional reactions to normal market movement. The convenient access is helpful, but the best use is purposeful rather than compulsive.
Where it saves time, and where it does not
The biggest friction removed is the transition from “I should check that” to actually checking it. A dedicated app reduces the number of decisions involved: which site to visit, where to sign in, and whether the page is designed for a phone. That is a small workflow improvement, but it is exactly the kind of improvement that makes an administrative task more sustainable.
It is also useful for separating account access from research. If I am only trying to review my TSP information, I do not need to begin with a search engine or sort through unrelated financial tools. That narrower path makes the app feel more dependable for a specific job, even though it does not replace the research needed for investment choices.
There is a trade-off in that narrow design. A user who wants one application to combine a TSP account with bank balances, brokerage accounts, debt tracking, spending categories, and long-term projections may prefer a broader personal-finance service. Those tools can provide a more complete overview, although they may not offer the same direct focus on the TSP account. I see the choice as one between depth of access to this account and breadth across an entire financial life.
The app is similarly not the right answer for someone who wants extensive educational guidance before making a decision. A dedicated account-access tool can make information easier to reach, but it should not be mistaken for personalized advice. If I were uncertain about contribution choices, risk, or retirement timing, I would use the app to access the account and consult appropriate guidance separately.
Useful habits that are easy to overlook
One practical habit is to use the app as a checkpoint before making a larger financial change elsewhere. For example, if I am revising my monthly budget, I can review the TSP account first so that retirement contributions are considered alongside rent, bills, and savings goals. This does not mean changing anything automatically; it simply keeps the retirement account from disappearing from the conversation.
A second habit is to keep account reviews tied to meaningful events rather than random notifications. A monthly budget session, an annual personal-finance review, or a change in employment circumstances gives the visit a reason. That approach reduces the risk of turning the app into a source of unnecessary daily worry while still keeping the account visible.
A third insight is that convenience can expose an important distinction between viewing and acting. I would use a quick mobile visit for orientation, then slow down whenever a decision could affect long-term savings. The app is strongest when it shortens access, not when it encourages hurried choices. A smaller screen and a busy moment are not ideal conditions for reviewing a complicated retirement decision.
Finally, I would treat any unexpected sign-in problem as a reason to stop and verify the situation rather than repeatedly trying random credentials. Financial-account access deserves a calm troubleshooting process. The app may make normal access easier, but it cannot remove the need for careful account security or accurate sign-in information.
How it compares with the usual alternatives
The most obvious alternative is using a phone browser. A browser can be flexible and may be preferable if you already have a trusted routine that works well. The dedicated app’s advantage is focus: it is designed around the TSP rather than asking you to navigate a general web session. For a person who checks the account from a phone regularly, that focused entry point is likely to feel more natural.
A desktop browser remains a better choice for users who prefer a larger screen, keep financial records open side by side, or want to think through a decision at a desk. I would choose the desktop for a longer review and the app for a quick account check. These are not competing choices in every situation; they serve different levels of attention.
General finance aggregators offer the opposite strength. They can help users see multiple accounts together and understand household finances in one place. However, their broad view may be less suitable when the task is specifically to access or review a TSP account. I would use an aggregator for a consolidated financial snapshot and this app for a more direct TSP-focused visit.
That distinction also explains why the app may feel limited to some people. Its value comes from not trying to become a universal money manager. If your main need is a single, clear route into your TSP account, that restraint is an advantage. If your main need is budgeting, forecasting, or comparing every financial account you own, another tool will likely fit better.
Reliability, audience, and the practical trade-offs
The app has built a strong user response, with a 4.8 average from around 5.5 thousand ratings and roughly 1.9 thousand written reviews. It has passed 500 thousand installs, which suggests that it is not an obscure experiment but a commonly used route for people managing this particular plan. Those figures do not guarantee that every device or account situation will feel identical, but they do make the app easier to take seriously as a regular utility.
Because it is free, the decision to try it is straightforward for eligible TSP users who meet the operating-system requirement. There is no purchase decision to weigh against occasional use. The more important question is whether you value direct mobile access enough to add another financial app to your phone.
The developer, FRTIB, is closely associated with the purpose of the application, which gives the app a clearer role than an unrelated third-party finance tool. Even so, I would keep normal caution around any account-access application. Use the official download route, protect the device, and avoid assuming that a convenient interface removes the need to review account details carefully.
One limitation of mobile access is that it can make a serious account feel deceptively simple. A quick glance is easy, but retirement planning is not. Users who are new to the TSP may still need separate explanations of their choices, contribution approach, and long-term goals. The app can support that process by making account information reachable, but it should not be the only source used to make an important financial decision.
Who should use it, and who should skip it
I would recommend Thrift Savings Plan to current TSP participants who want a straightforward mobile route to their account. It is especially suitable for people who handle most routine tasks on a phone, dislike repeated browser navigation, or want to fit a short account review into an existing budgeting routine. The free price and Everyone rating also make it approachable for a wide range of users, provided their device meets the required operating-system version.
I would be more cautious about recommending it to someone who rarely uses mobile financial tools or prefers handling retirement matters exclusively on a computer. In that case, the app may add little beyond a second access method. I would also point users toward a broader financial application if their priority is tracking spending, combining several institutions, or building an all-in-one household dashboard.
It is not the right standalone solution for someone looking for personalized retirement advice. Nor would I suggest using it as a reason to check market-related information constantly. Its best role is quieter and more practical: make the TSP easier to reach, then let the user decide when a visit is actually worthwhile.
My final view after using it
Thrift Savings Plan earns its place on a phone by solving a recurring access problem rather than trying to do everything. I found the strongest benefit in the reduced effort between remembering an account task and completing a quick review. That makes it useful for regular financial routines, preparation for a wider review, and those moments when waiting for a desktop would only encourage procrastination.
The trade-off is a narrow scope. It is not a replacement for a full personal-finance dashboard, a larger-screen review, or informed retirement guidance. Users should also resist turning easy access into constant checking or rushed decisions. The app works best when convenience supports discipline instead of replacing it.
My recommendation is simple: if you have a TSP account and want direct, free mobile access, this is a sensible app to keep available. It saves small amounts of time, removes unnecessary navigation, and keeps one important financial task within reach. If you want a complete financial command center, choose a broader tool and treat this app as the focused companion it is.
Frequently Asked Questions
01What is the Thrift Savings Plan app used for?
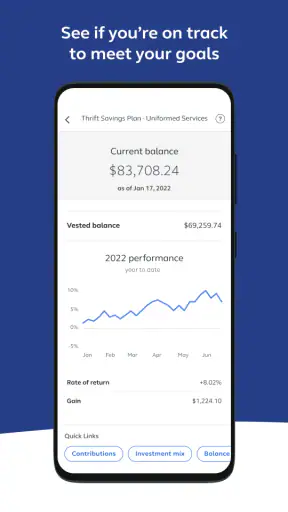
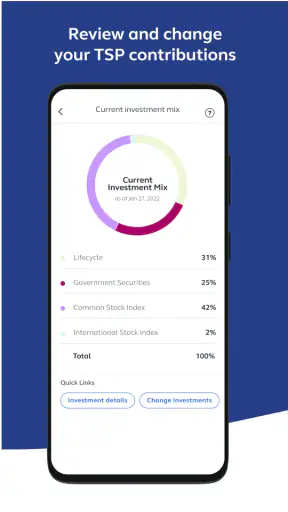
The Thrift Savings Plan app is designed to give eligible federal employees, members of the uniformed services, and other participating account holders convenient access to their TSP information. After signing in, you can generally review your balance, check contributions, monitor investment allocations, view account activity, and manage selected account services without needing to use a desktop browser every time.
02Who can use the Thrift Savings Plan app?
Access is intended for people who have an eligible Thrift Savings Plan account, including qualifying federal civilian employees, members of the military, and certain other participants. You will need valid account credentials and may be asked to complete identity verification or multi-factor authentication. The app is not a general investment platform, so users without a TSP account may have limited or no practical use for it.
03Can I change contributions or investments through the app?
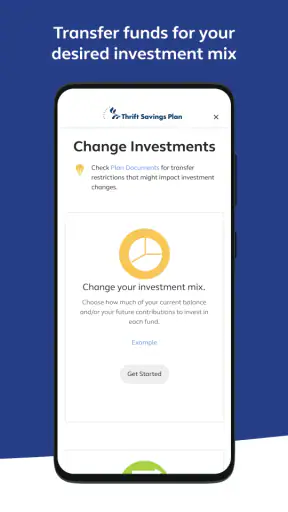
Depending on your account status and the services currently supported, the app may allow you to review or manage contribution information, investment allocations, interfund transfers, or other account preferences. Available options can vary by participant type and security requirements. Before confirming a transaction, carefully review the details because investment changes can affect your retirement savings and may not take effect immediately.
04Is the Thrift Savings Plan app safe to use?
The app is intended to provide secure access to sensitive retirement-account information through login protections and additional verification features. For the safest experience, download it only from the official Google Play Store or Apple App Store, keep your device and operating system updated, and avoid signing in over unsecured public networks. Never share your password, verification codes, or other account details with anyone.
05Are there fees for using the Thrift Savings Plan app?
Downloading and using the official app is generally not presented as a separate subscription service, but that does not mean every TSP-related transaction or investment activity is free of costs. Account expenses, fund fees, loan charges, withdrawal rules, or tax consequences may apply according to the plan’s terms. Review the official fee and transaction information before making financial decisions through the app.


